Bessent Issues Brave New Rules for Bond Market Stability
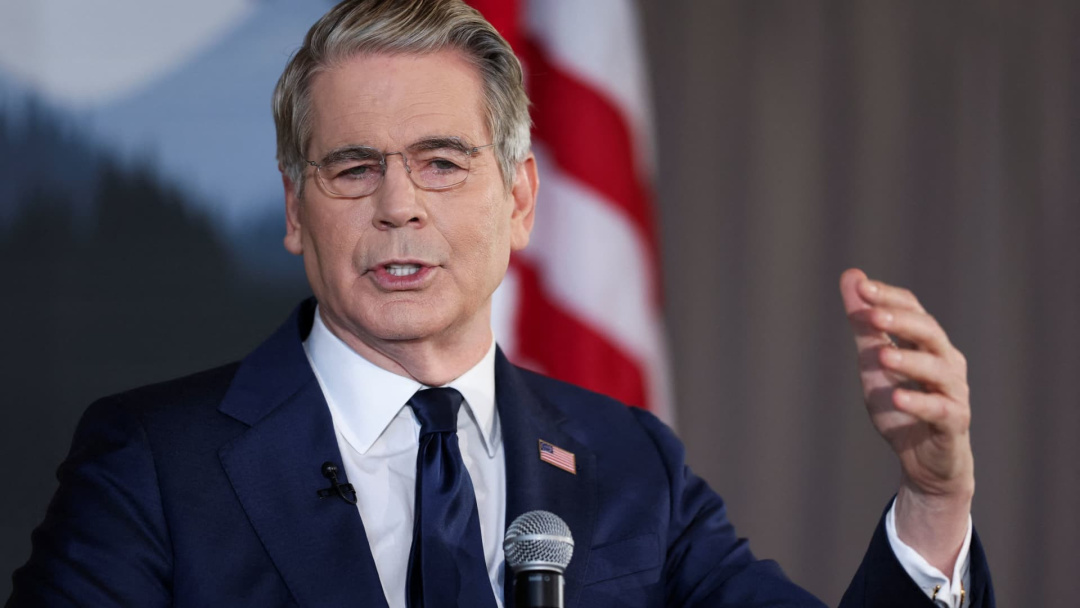
U.S. Treasury Secretary Scott Bessent confidently took center stage during a recent G20 gathering, proclaiming the U.S. bond market as a bastion of stability. While finance ministers and central bank governors were busy trying to keep their coffee from spilling, Bessent insisted that the current spike in the 10-year Treasury yield is simply a minor blip, akin to a toddler's temper tantrum. He reassured attendees that, after all, what happens over a month really doesn’t matter—unless, of course, it involves his golf score.
In what can only be described as a masterclass in bureaucratic optimism, Bessent introduced the newly minted 'Bessent Doctrine of Market Fluidity.' Under this doctrine, officials will now categorize monthly yield changes as 'temporary emotional responses' to the relentless pressures of global economic dynamics. In a bold move that surely impressed everyone in the room, he emphasized that the real heroes—the bond market investors—will surely recognize when to hold and when to fold, much like their poker-playing counterparts.
Still Beats Watergate:
Sponsor success. Continue reading:
But Bessent didn’t stop there; he also unveiled the U.S. Treasury’s new strategic initiative: the 'Market Stabilization Advisory Committee for Momentary Variations.' This elite group promises to handle short-term fluctuations with the gravitas of a nuclear launch codes committee, ensuring that any jump in yields is treated with the utmost seriousness—unless it happens before lunch.
Bessent's Bold New Success Metric
As if to double down on his unwavering confidence, Bessent closed his remarks with an audacious new metric for success: the 'Panic-Induced Yield Turbulence Index' or PIYTI, designed to gauge how many crises can occur before anyone actually cares. The ambitious target? Zero, naturally, because who wouldn’t want to live in a world where bond yields are as stable as the administration’s talking points?
Applied to you
Even as finance ministers nodded along with their best poker faces, it became increasingly clear that this was just another day in the unpredictable world of finance, where the jargon is as colorful as the forecasts are grim. And thus, Bessent stepped back into the fray, leaving behind a trail of confusion and misplaced trust in the stability of the very markets he claimed to protect.
In the end, the real question remains: with such a buoyant outlook, will the bond market finally decide to take a vacation of its own? Or will it dance on the edge of chaos forever more?